ETA and Search-Fund Buyers Using SBA Financing
September 28, 2026
ETA buyers can use SBA 7(a) financing for an eligible change of ownership. The strongest files connect the buyer's transferable experience with the target's operations, rely on supportable historical cash flow, and present a clear plan for equity, working capital, seller transition, and post-closing leadership.
More professionals are exploring business ownership after careers in management, finance, consulting, sales, technology, and operations. Stanford's search-fund research reflects the continued development of this acquisition path. At the same time, a recent business-acquisition analysis reported that 78% of surveyed buyers expected to use SBA-backed financing, showing how central the program has become to smaller acquisitions.
A self-funded searcher usually finances the search personally and raises equity around a specific deal. A traditional search fund raises capital before the search and may have multiple investors. That distinction matters because ownership, guarantees, equity sources, and control must fit SBA eligibility and lender requirements.
Lenders examine the buyer's resume, industry familiarity, management experience, personal financial position, credit history, and plan for full-time involvement. Direct industry experience helps, but relevant leadership and operating skills can also matter when the buyer explains how those skills transfer to the target company.
First-time buyer reviewing an SBA acquisition opportunity
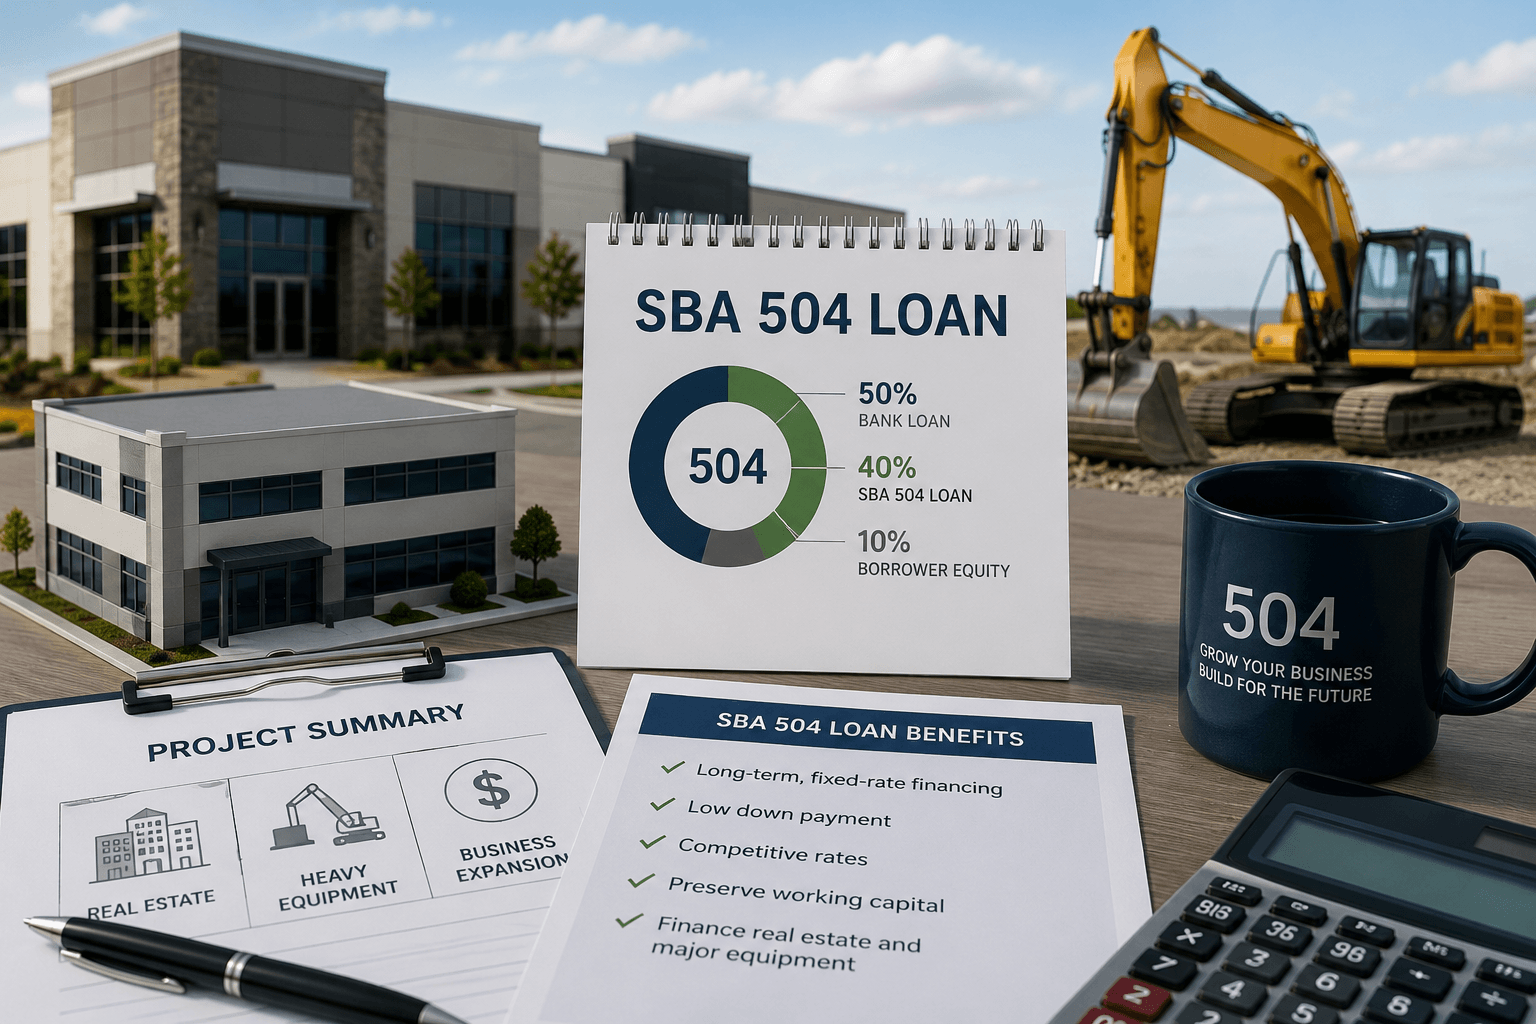
The purchase price is only one part of the project. Buyers must account for working capital, closing costs, professional fees, possible real estate, and transition expenses. The proposed seller note and outside-investor structure should be reviewed early, especially under SOP 50 10 v8.1 rules that take effect Oct 1, 2026.
SBA Loan Guy helps acquisition entrepreneurs evaluate financing readiness, organize the buyer profile, review the target's cash flow, and approach lenders whose credit appetite fits the transaction. That preparation is valuable before an LOI, during diligence, and when the buyer needs to compare competing structures.
Potentially. A degree alone does not qualify a deal, but relevant experience, financial capacity, a strong target company, and an executable operating plan can support the request.
Outside equity may be possible, but ownership, control, guarantees, and the source of the injection must meet current SBA and lender rules.
Before signing a restrictive LOI. Early feedback can reveal whether the purchase price, working-capital need, and ownership structure are realistic.
ETA buyers are bringing new talent into the small-business acquisition market, but a credible financing plan must connect the buyer, the business, and the capital structure. Use the SBA Loan Guy blog for more acquisition-financing guidance or book a call before committing to a deal.
Stanford 2024 Search Fund Study

A distilled, 0–100 snapshot of how fundable you are based on credit, cash flow, equity, and documentation. Plus the top fixes to raise your score fast.
A curated shortlist of lenders that fit your profile and use of funds, with why each is a fit and exactly what they’ll want to see.
A tailored, step-by-step list of required docs and forms (formats, who provides them, and common pitfalls to avoid).
A realistic week-by-week path from pre-qual to closing, with milestones, dependencies, and an estimated target funding date.
Hands-on prep and documentation for SBA disaster programs (EIDL and others), including submissions, follow-ups, and guidance through appeals or requests for more info.
We prepare your application, match you with the
right lenders, and guide you until funding.