Debt Service Coverage Ratio and SBA Loans: Why the Math Mat...
September 28, 2026
Debt service coverage ratio compares available business cash flow with required debt payments. It is one of the clearest ways lenders judge whether the loan payment is realistic.
The official U.S. Small Business Administration provides the program framework, but lender appetite still matters. SBA lenders review the same general categories, yet they do not all view every industry, borrower, or loan purpose the same way.
Most delays happen before the file ever reaches a final decision. A borrower may have enough revenue, enough experience, and a reasonable request, but if the story is not organized, the lender has to assemble the case from scattered documents.
That is why the SBA Loan Guy process focuses on readiness first. The file should show what the business does, why the money is needed, how repayment works, and where the lender may need clarification. A prepared package makes the conversation easier for everyone involved.
Modern office space for small business expansion planning
Many SBA problems are fixable when they are caught early. They become harder to fix after a lender has already formed an opinion of the file.
Borrowers can also use resources like SCORE and local business groups such as the Greater Houston Partnership for broader business planning support. For the financing package itself, the key is to build a lender-ready case before the file is submitted.
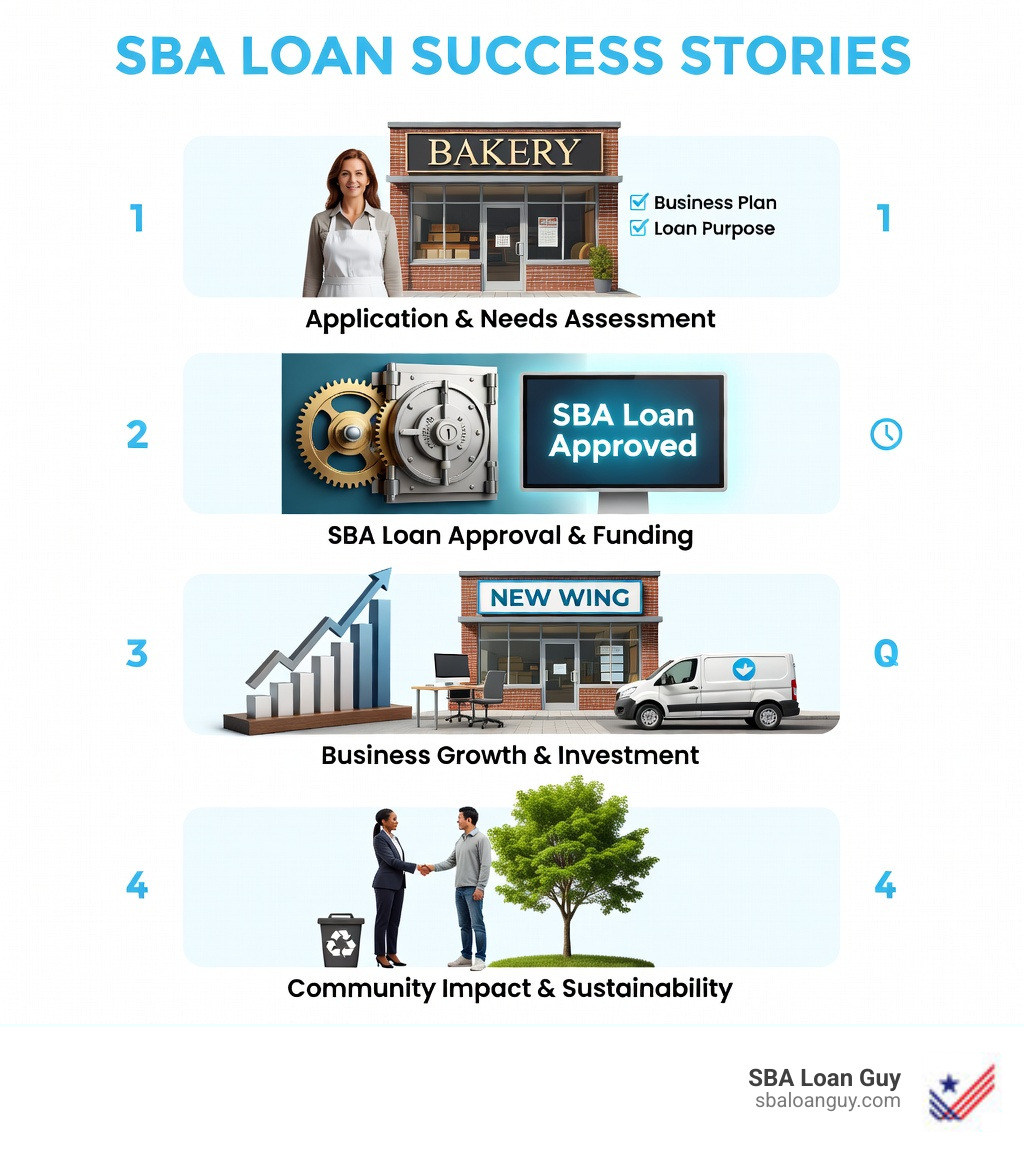
SBA Loan Guy was built to make the SBA process simpler, more transparent, and faster for business owners. The team reviews the funding goal, prepares the application package, identifies likely lender questions, and matches the file with lenders that fit the borrower profile and use of funds.
That preparation is especially useful for borrowers who are comparing SBA 7(a), SBA Express, or SBA Disaster Loan options. The right loan path depends on the purpose, size, urgency, documents, and business story.
DSCR stands for debt service coverage ratio. It measures whether cash flow is enough to cover debt payments.
Sometimes, but tight coverage usually leads to more questions, stronger conditions, or lender hesitation.
A stronger equity injection, lower purchase price, seller note structure, longer amortization, or clearer add-backs may help.
Debt Service Coverage Ratio and SBA Loans: Why the Math Matters comes down to preparation, fit, and structure. A business owner does not need to know every SBA rule before applying, but the file does need to answer the lender’s biggest questions clearly. Visit the SBA Loan Guy blog for more SBA financing guides, or book a call before you submit a package or sign deal terms.

A distilled, 0–100 snapshot of how fundable you are based on credit, cash flow, equity, and documentation. Plus the top fixes to raise your score fast.
A curated shortlist of lenders that fit your profile and use of funds, with why each is a fit and exactly what they’ll want to see.
A tailored, step-by-step list of required docs and forms (formats, who provides them, and common pitfalls to avoid).
A realistic week-by-week path from pre-qual to closing, with milestones, dependencies, and an estimated target funding date.
Hands-on prep and documentation for SBA disaster programs (EIDL and others), including submissions, follow-ups, and guidance through appeals or requests for more info.
We prepare your application, match you with the
right lenders, and guide you until funding.