August 19, 2026
If there's one SBA loan program you'll hear about most, it's the 7(a). It's the "all-purpose" loan, and for good reason, it can be used for almost anything a growing business needs.
Buying an existing business or franchise
Working capital for day-to-day operations
Purchasing equipment, furniture, or inventory
Buying or renovating real estate your business occupies
Refinancing existing business debt
The government guarantees a portion of the loan to the lender. That guarantee is what makes banks comfortable saying yes to businesses they might otherwise consider too risky. You're still borrowing from a private lender, the government is just backing part of the risk.
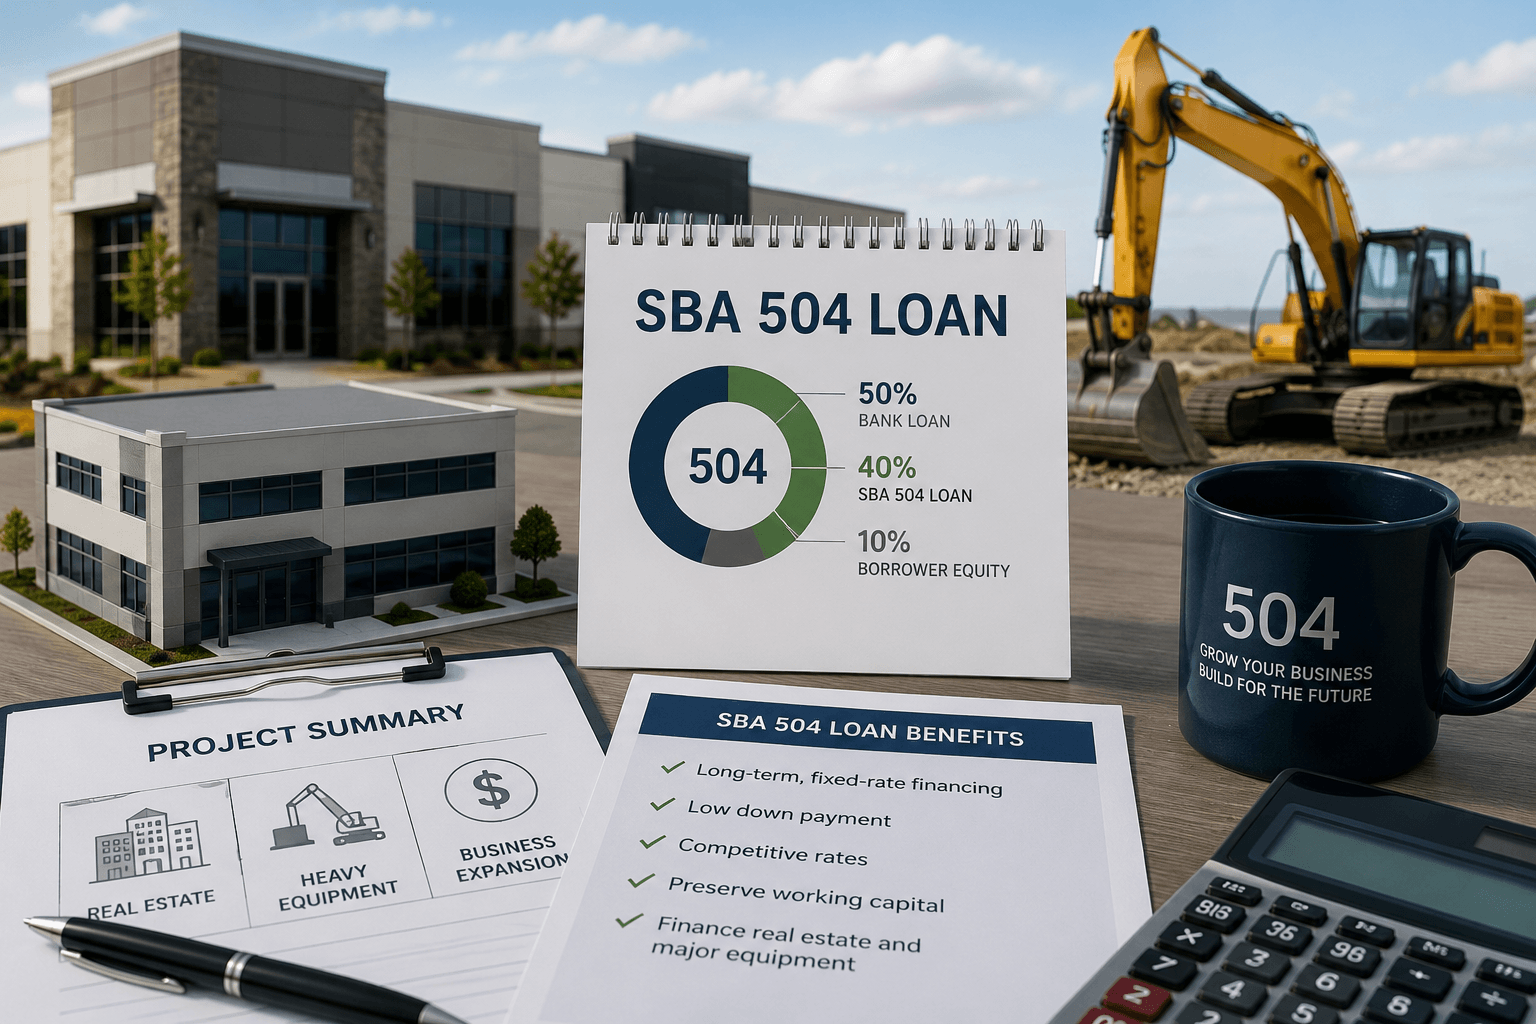
How is a 7(a) different from a 504 loan?
7(a) is the flexible, general-purpose option. 504 is specifically for major fixed assets like real estate and heavy equipment.
How fast can I get funded?
Typically around 10 weeks, faster with a Preferred Lender.
If you need financing and aren't sure which SBA product fits, the 7(a) is usually the right starting question to ask. Visit our blog for more, or reach out to see if you prequalify.
U.S. Small Business Administration
SCORE — free SBA business mentoring

A distilled, 0–100 snapshot of how fundable you are based on credit, cash flow, equity, and documentation. Plus the top fixes to raise your score fast.
A curated shortlist of lenders that fit your profile and use of funds, with why each is a fit and exactly what they’ll want to see.
A tailored, step-by-step list of required docs and forms (formats, who provides them, and common pitfalls to avoid).
A realistic week-by-week path from pre-qual to closing, with milestones, dependencies, and an estimated target funding date.
Hands-on prep and documentation for SBA disaster programs (EIDL and others), including submissions, follow-ups, and guidance through appeals or requests for more info.
We prepare your application, match you with the
right lenders, and guide you until funding.