August 19, 2026
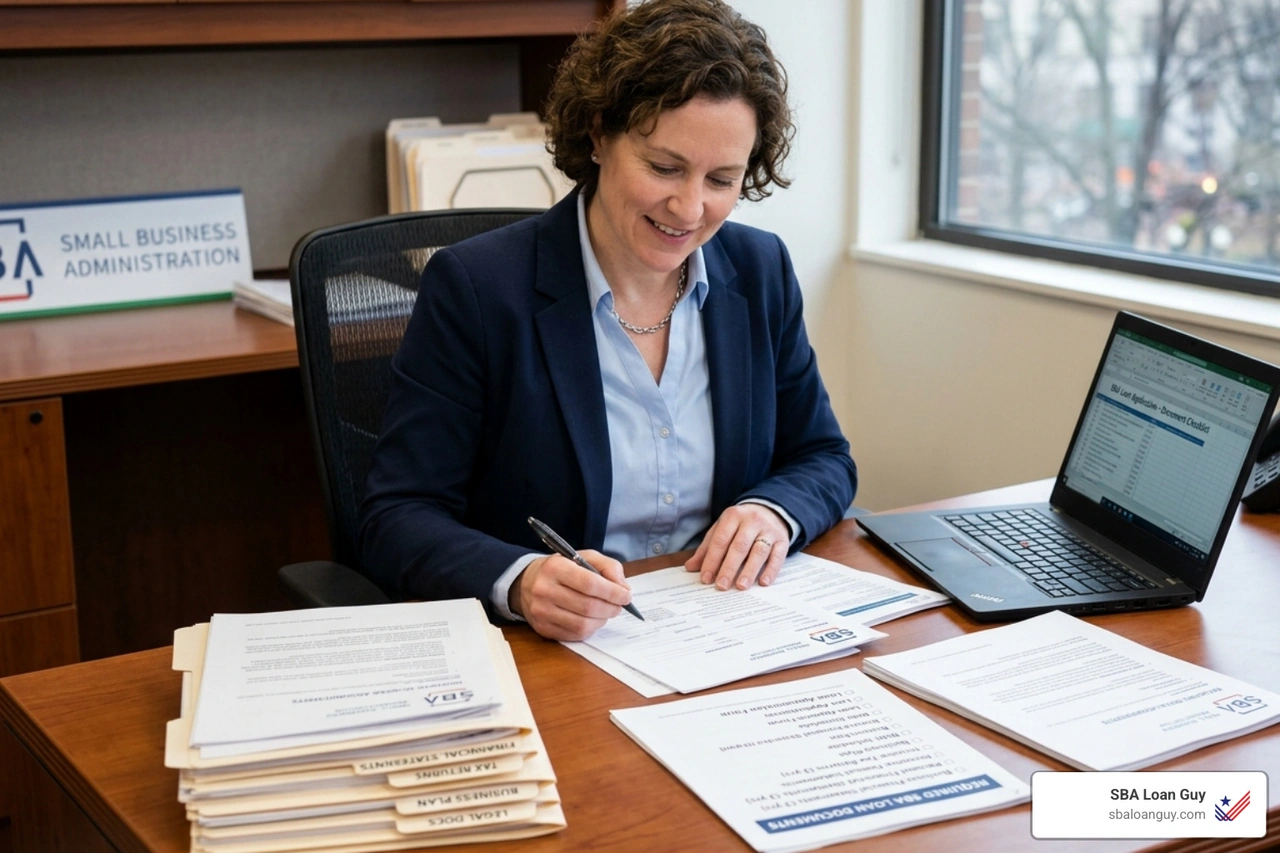
Most SBA loan delays trace back to the same cause: someone applied before they had their documentation together. Here's what to gather before you start.
For-profit business operating in the U.S.
U.S. citizen or Legal Permanent Resident ownership
Good personal and business credit history
Cash flow sufficient to cover the new loan payment
Some owner equity in the deal, often around 10%
For loans above roughly $350,000, expect the lender to ask about collateral, something of value the bank can claim if the loan isn't repaid. They'll also typically want a personal guarantee, meaning you're personally on the hook even if the business itself closes.
What if my credit isn't perfect?
It's not automatically disqualifying. Lenders weigh the full picture, cash flow and collateral matter too.
Do I need collateral for every SBA loan?
Smaller loans may not require it. Larger ones usually do.
Getting your documentation together before you apply is the single biggest thing you control in this process. Visit our blog for a deeper walkthrough, or reach out and we'll tell you exactly what your file is missing.
U.S. Small Business Administration
SCORE — free SBA business mentoring

A distilled, 0–100 snapshot of how fundable you are based on credit, cash flow, equity, and documentation. Plus the top fixes to raise your score fast.
A curated shortlist of lenders that fit your profile and use of funds, with why each is a fit and exactly what they’ll want to see.
A tailored, step-by-step list of required docs and forms (formats, who provides them, and common pitfalls to avoid).
A realistic week-by-week path from pre-qual to closing, with milestones, dependencies, and an estimated target funding date.
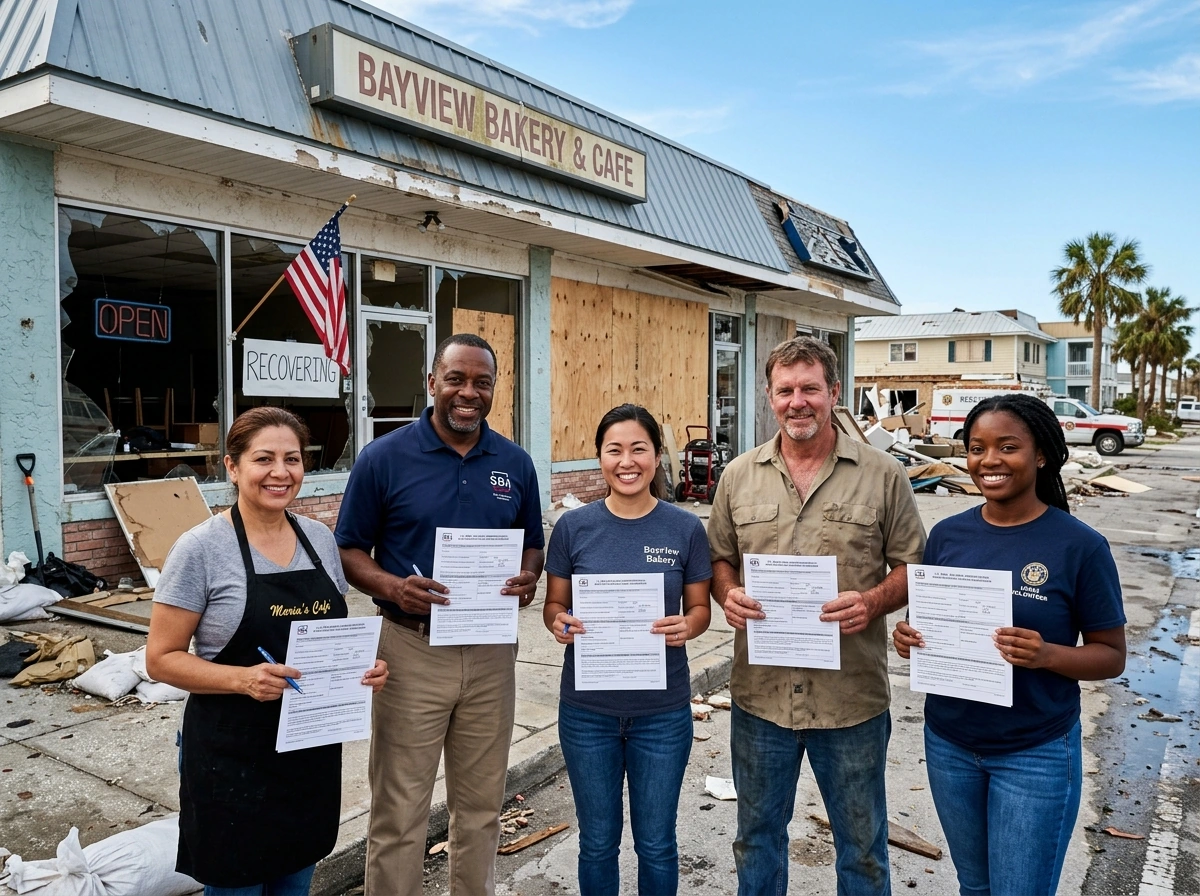
Hands-on prep and documentation for SBA disaster programs (EIDL and others), including submissions, follow-ups, and guidance through appeals or requests for more info.
We prepare your application, match you with the
right lenders, and guide you until funding.