Houston SBA Loans and Acquisition Cash Flow
September 28, 2026
SBA lenders usually begin with tax returns and historical financial statements, then adjust for documented nonrecurring expenses and owner-specific items. They compare the resulting cash flow with all required debt payments. The calculation must support repayment under SBA rules and the individual lender's credit policy.
Projections can explain a buyer's operating plan, but lenders want proof that the business has already produced enough cash to support the request. They may review several years of tax returns, interim statements, bank activity, and revenue trends. A sudden improvement needs documentation, especially when the strongest performance appears only in the current year.
The new SOP 50 10 v8.1 becomes effective on Oct 1, 2026, and places updated change-of-ownership guidance in Appendix 15. Buyers should have their lender confirm which version applies based on when the loan receives an SBA loan number.
Sellers often present discretionary earnings with add-backs for personal expenses, one-time costs, or excess owner compensation. Some adjustments may be reasonable, but lenders do not automatically accept every item in a broker package. Each material add-back should be supported by tax returns, general-ledger detail, invoices, or another clear record.
The lender evaluates the SBA payment along with other obligations that will continue after closing. A seller note with current payments, equipment debt, real-estate financing, or other acquisition debt can reduce coverage. Buyers should model the full structure before negotiating the final purchase price.
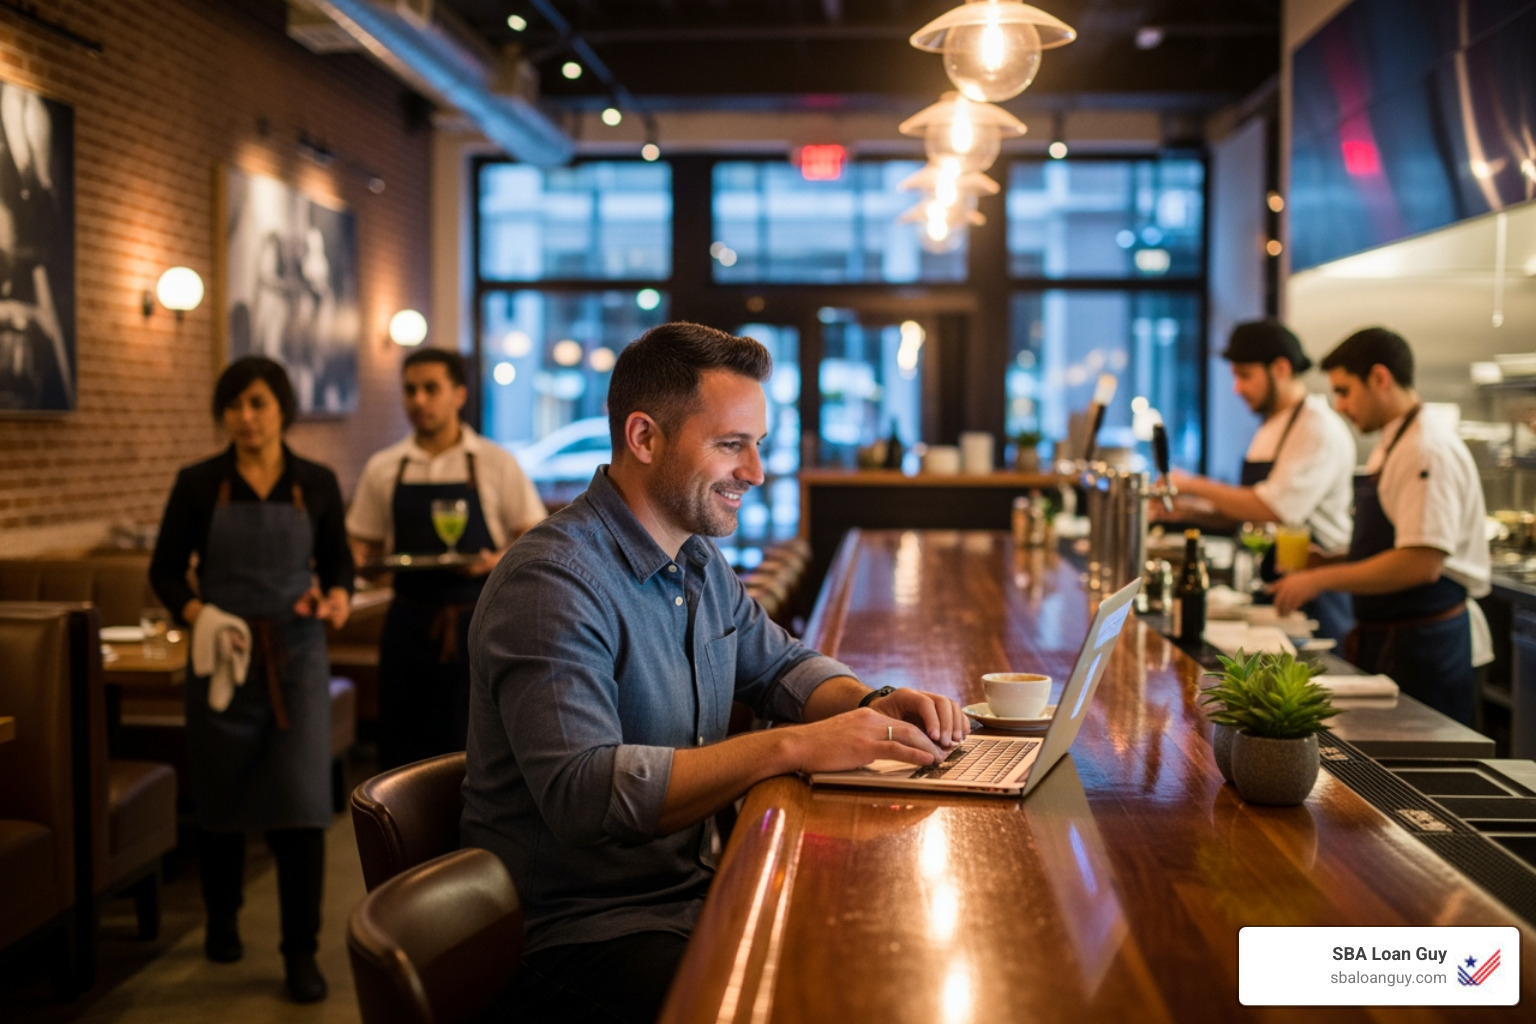
Buyer and advisor discussing a Houston business acquisition
Houston businesses may face industry-specific volatility, insurance costs, storm exposure, construction cycles, energy-market concentration, or rapid working-capital swings. These factors do not automatically prevent financing, but they should be explained in the lender narrative and reflected in the cash-flow model.
SBA Loan Guy helps buyers normalize the target company's cash flow, identify weak assumptions, organize supporting documents, and match the request with lenders that understand the industry and transaction type. The goal is to test the deal before the buyer spends weeks in underwriting.
Projections can provide context, but buyers should not assume expected improvements will replace weak historical repayment ability.
No. SBA rules provide a framework, but lenders may apply different documentation standards and credit policies.
Sometimes, but only when the structure satisfies current SBA and lender requirements. A seller note with payments also affects debt-service coverage.
Strong Houston SBA loan applications show how the business performed historically, which adjustments are supportable, and how every layer of debt will be paid. Buyers should run that analysis before finalizing the offer. Visit the SBA Loan Guy blog or schedule a financing review for an acquisition you are evaluating.

A distilled, 0–100 snapshot of how fundable you are based on credit, cash flow, equity, and documentation. Plus the top fixes to raise your score fast.
A curated shortlist of lenders that fit your profile and use of funds, with why each is a fit and exactly what they’ll want to see.
A tailored, step-by-step list of required docs and forms (formats, who provides them, and common pitfalls to avoid).
A realistic week-by-week path from pre-qual to closing, with milestones, dependencies, and an estimated target funding date.
Hands-on prep and documentation for SBA disaster programs (EIDL and others), including submissions, follow-ups, and guidance through appeals or requests for more info.
We prepare your application, match you with the
right lenders, and guide you until funding.